

In 2022, Sri Lanka’s sovereign debt crisis pushed inflation above 70% and wiped out foreign reserves almost overnight.
Rural households faced the greatest impact. About 74% of Sri Lankan adults have a bank account, but access outside urban centres has traditionally been facilitated by cooperative societies rather than commercial banks.
These cooperatives are foundational to Sri Lanka’s financial landscape. For decades, they have run on paper ledgers and manual processes. That is the gap Nanosoft is addressing.
What Nanosoft Does
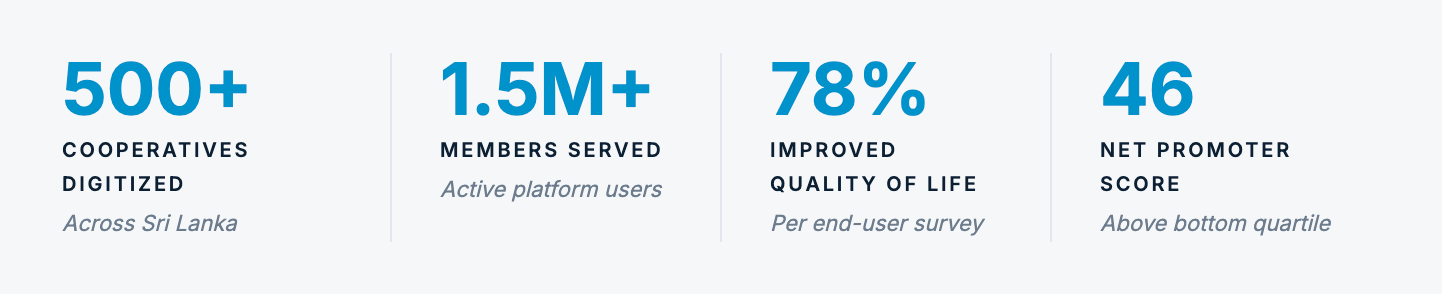
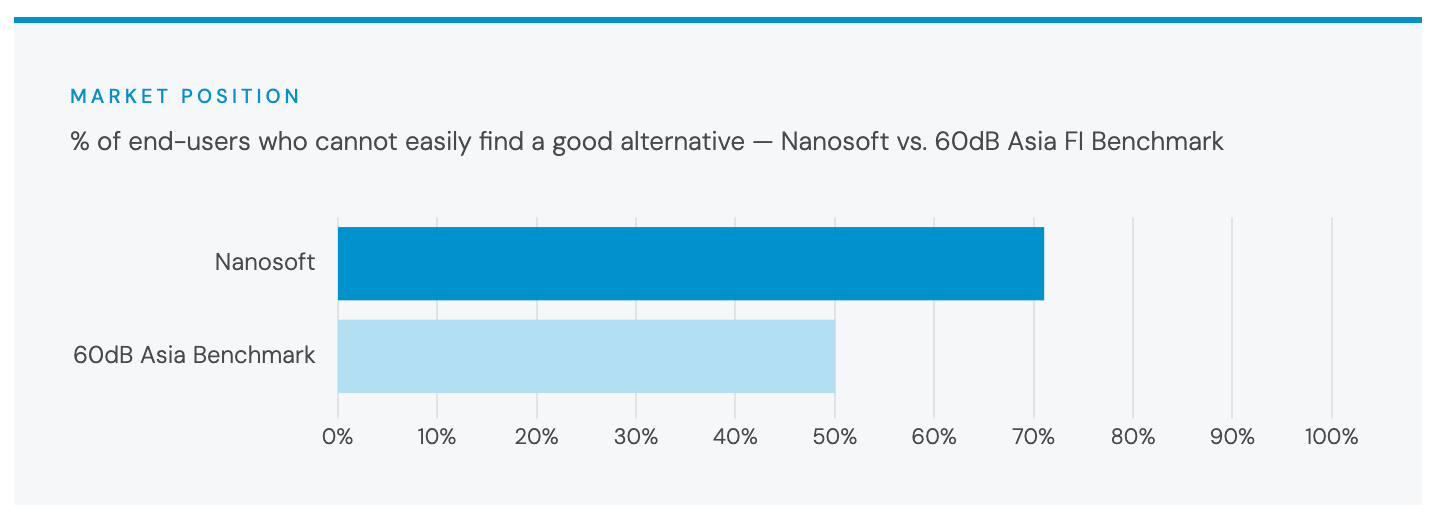
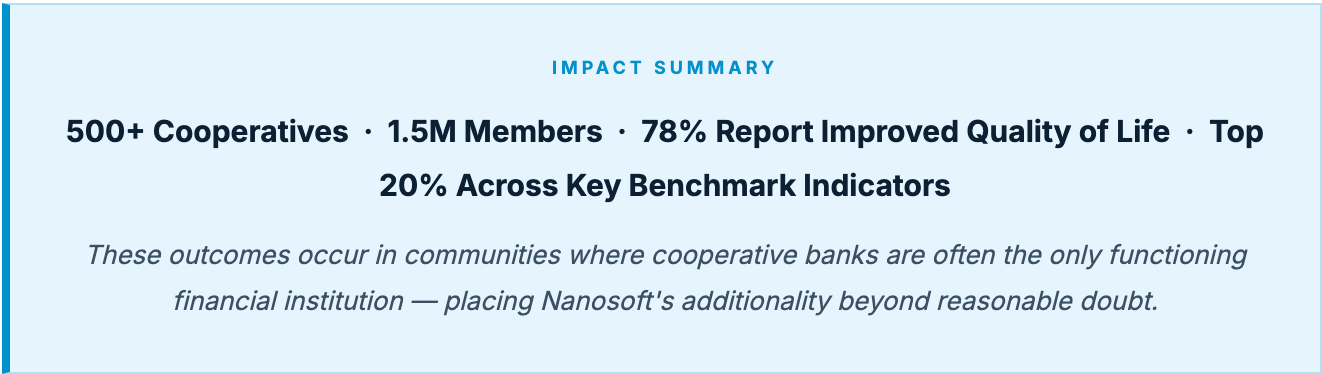
Nanosoft's Smart COOP platform digitises cooperative banks end-to-end: core banking, a member-facing mobile app, and a field collection tool for door-to-door officers. Deployment takes 30 days. It is among the very few fintechs building specifically for this sector, and 71% of its users say they cannot find a comparable alternative, placing it in the top 20% of the 60 Decibels1 Asia Financial Inclusion benchmark.
The Impact
In June 2023, 60 Decibels conducted 125 phone interviews with Smart COOP end-users across Sri Lanka, commissioned under FMO’s Reducing Inequalities Initiative. Interviews were conducted in Sinhala, randomly selected from Nanosoft’s end-user database, with a 65% response rate, 90% confidence level, and 5% margin of error.
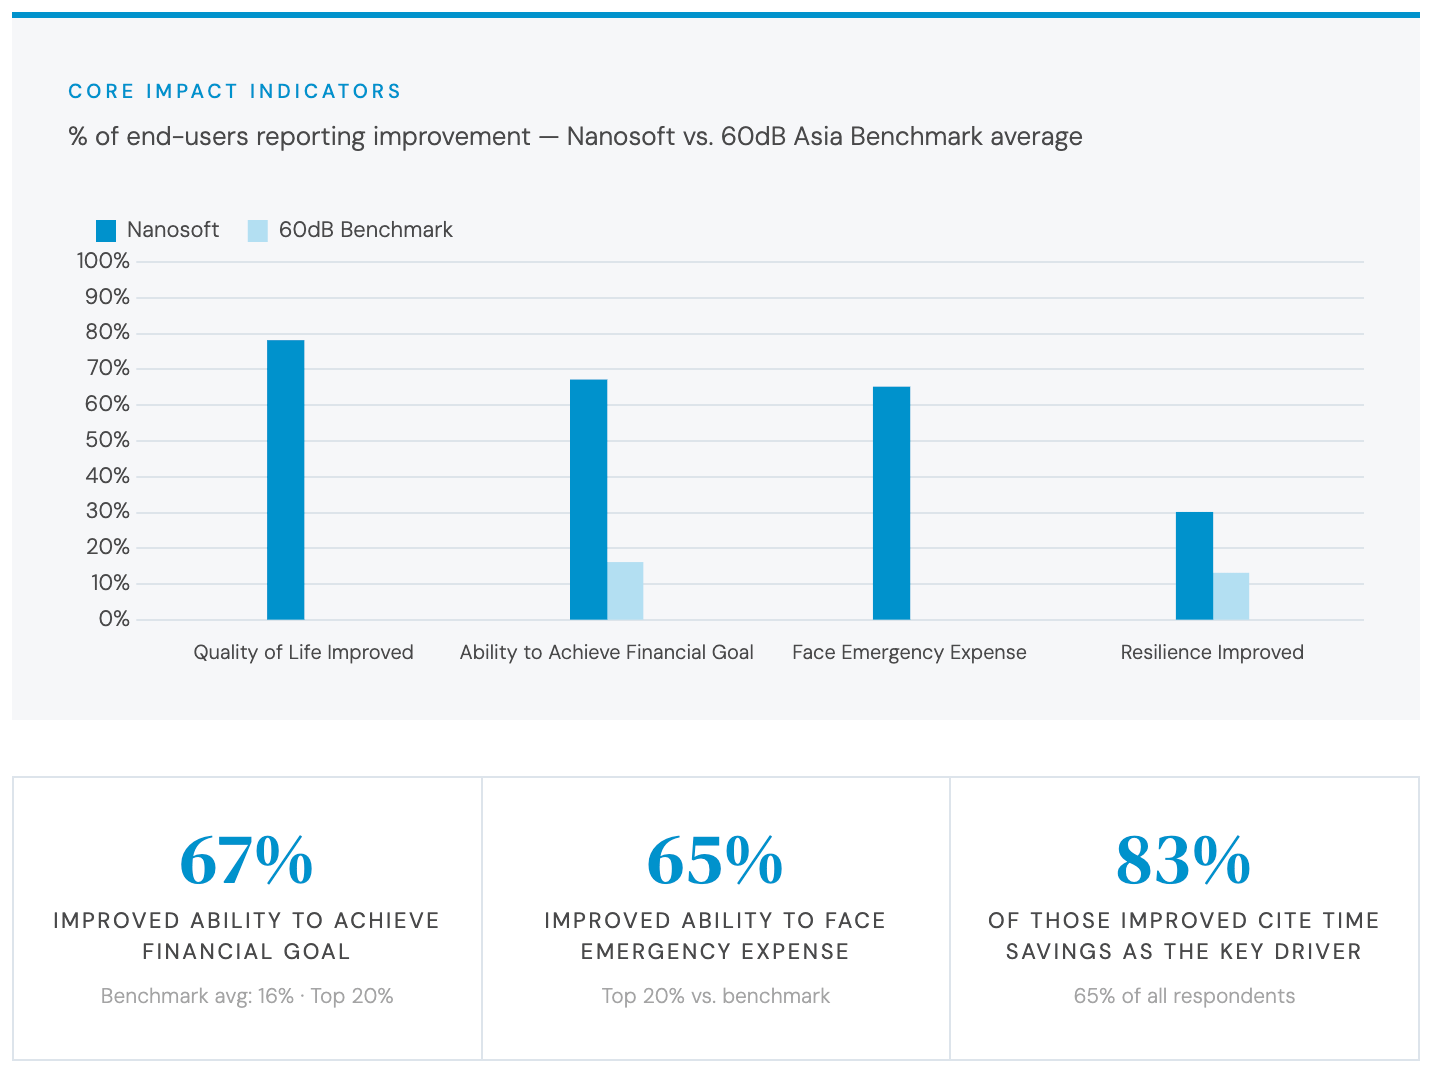
78% of end-users report that their quality of life has improved as a result of using Smart COOP. The three most cited drivers are:
Time savings (83% of those reporting improvement)
Improved emotional and physical well-being (40%)
Better savings behaviour (28%)
Time savings deserve unpacking. For a rural household in Sri Lanka, a trip to the bank is not a short errand — it can mean a half-day journey, lost income, and compounding friction for every financial task: checking a balance, paying a utility bill, reviewing a loan schedule. Smart COOP removes that friction entirely.
“We no longer need to go to the bank to check our account balance, fixed deposit interest, loan dues or loan details.”
Male end-user, age 33
On financial resilience — a critical metric in a post-crisis context — only 18% of users say it would be difficult to come up with the equivalent of a month’s emergency fund within 30 days. 65% report their ability to face a major emergency expense has improved because of Nanosoft, placing the platform in the top 20% of its peer benchmark.
The leading financial goals cited are saving more money (32%), starting a new business (10%), and acquiring housing or property (8%). In the aftermath of a crisis that eroded household savings, the ability of a financial tool to move the needle on goal attainment is not assumed. The data indicates Smart COOP is doing this.
Inclusivity Ratio — A Key Caveat
For impact investors and development finance institutions, reach matters as much as depth of impact. A product that delivers strong outcomes for a relatively well-off segment carries a different profile than one delivering outcomes for those most excluded from the formal system.
Nanosoft’s data presents a mixed picture. 77% of end-users are rural, and the platform serves communities where cooperative banks are often the only functioning financial institution. The user base sits largely within the low-to-middle income range.
However, the Inclusivity Ratio — a 60 Decibels metric measuring reach to lower-income users relative to the national population — stands at 0.29, in the bottom 20% of benchmarks. Only 1% of end-users live under $3.20 per day, compared to 11% of the national population. The cooperative banking entry point may itself be a partial constraint: members of functioning cooperatives tend not to be the most economically vulnerable.
The Gender Gap
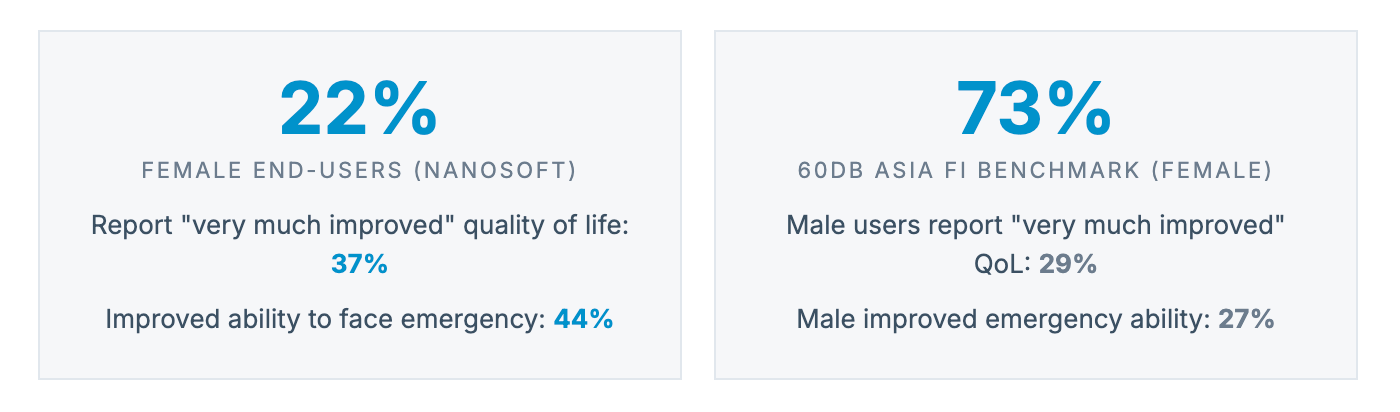
The gender dimension compounds the picture. Only 22% of end-users are female, which is below the 60 Decibels Fl benchmark for female reach in Asia (73%). However, female end-users report a better experience and a higher impact from Nanosoft compared to men. By understanding female drivers, Nanosoft can increase its female end-user base.
We can now review the loan information, like due dates and amount details, that, if missed, we’ll have to pay interest. Now we don’t miss [the payment days] because we can check our reminders easily.
Female, 51
The cost of this gap is visible in the data: female users report a “very much improved” quality of life at 37%, compared to 29% for men, and improved ability to face emergency expenses at 44% versus 27%. The product is working more effectively for women than for men, among the minority currently using it.
Closing the gender gap is both an equity argument and a product performance one. A practical lever exists: prioritising cooperatives with higher female membership ratios — those serving garment workers, tea plantation communities, or informal traders — during partner onboarding.
The Larger Argument
Sri Lanka’s path to economic recovery runs, in part, through the strengthening of household-level financial resilience — the ability of families to save, absorb shocks, and invest in their futures. That is not a task that commercial banks, oriented toward urban markets and larger transactions, are positioned to lead. It has historically fallen to cooperative institutions.
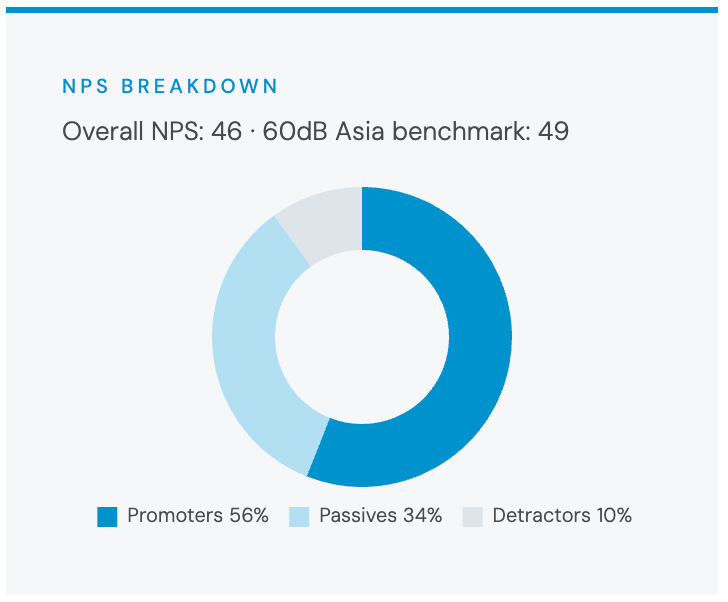
What Nanosoft is doing — building digital infrastructure for that layer — is structurally relevant in the way that financial inclusion work tends to be: incremental, distributed, and durable. Households are saving more. They are better equipped to face emergencies. They are spending less time on financial administration. These are outcomes that would not have occurred without the platform.
60 Decibels is a global, tech-enabled impact measurement company that brings speed and repeatability to social impact measurement and customer insights. They provide genuine benchmarks of impact performance, enabling organisations to understand impact relative to peers and set performance targets. They have a network of 1,200+ researchers in 97+ countries, and have worked with more than 800 of the world’s leading impact investors, companies, foundations, corporations, NGOs, and public sector organisations.