

Every week, another founder posts a jubilant LinkedIn update: “Thrilled to announce we’ve closed our seed round.” The replies are warm. The momentum feels real. And then, eighteen months later, quietly, the company stops posting.
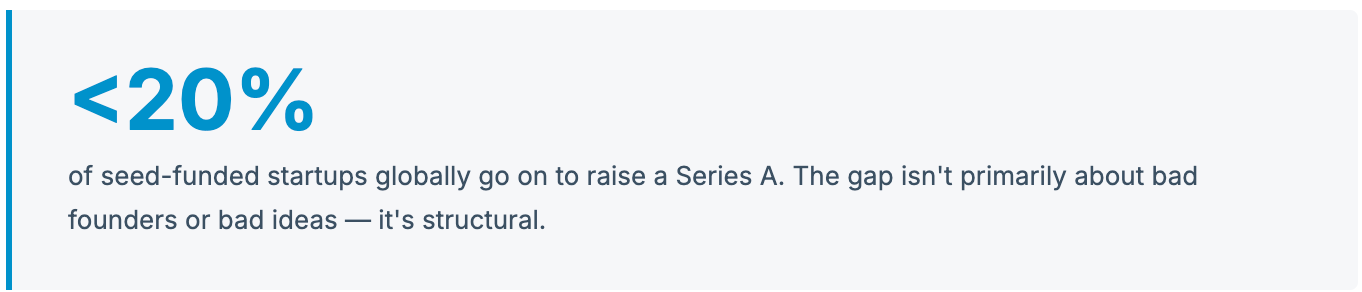
This is the Series A crunch. It’s not a secret, but it’s still not talked about honestly enough.
The Expectation Gap
When a seed investor writes a cheque, they’re buying optionality. They know most of their bets won’t work. The whole model is built around a few outsized winners covering the losses. That’s not cynical — it’s just the arithmetic of venture.
Series A investors operate on entirely different terms. By the time a founder walks into that room, the story must be one of proof, not potential. Specifically: proof of repeatable revenue, clear unit economics, and an addressable market large enough to justify a $500M+ outcome. That’s the bar, whether or not anyone says it out loud in the first meeting.
The problem is that most seed rounds are sized to build a product and find early customers — not to definitively answer the questions Series A investors need answered. Founders spend eighteen months building, then discover they’ve run out of runway just as things start getting interesting.
The Three Real Killers
Metrics that don’t translate
A seed deck can celebrate user growth, engagement, and NPS. A Series A deck has to show revenue, retention, and a path to margin. Founders who spend their seed capital optimising for the wrong metrics arrive at the next fundraise with an impressive story but an unreadable financial model.
Market sizing that doesn’t survive scrutiny
“Our TAM is $50 billion” is a seed-stage sentence. Series A investors will want to know what percentage of that market is genuinely serviceable, how you reach it, and why you win it competitively. Vague market claims that worked at seed become liabilities twelve months later.
Hiring ahead of the model
The temptation after closing a seed round is to build the team you want rather than the team you need. Scaling headcount before achieving product-market fit is the most reliable way to burn runway without building evidence — which is exactly what a Series A requires.
What Changes If You Know This From Day One
The founders who navigate this well treat their seed round as a Series A prep exercise. Every dollar is allocated against a question: what does this help us prove? They define their Series A metrics before they’ve spent a dollar of seed capital, and they build their company backwards from those targets.
This sounds obvious. Very few founders actually do it.
The other shift is in investor selection. Not every seed investor is positioned — or motivated — to help you get to Series A. Some are spray-and-pray funds who move on quickly. The founders who make it tend to be the ones who raised seed capital from investors with the network, the reputation, and the genuine interest to make introductions when the time comes. That’s a due diligence question worth asking before you sign a term sheet.
The nVentures Takeaway
Define your Series A metrics on day one of your seed round — before you’ve spent a dollar.
Ask every prospective seed investor: what does your track record look like getting portfolio companies to Series A? Their answer tells you more than their term sheet.
Treat every hire and every dollar as evidence. If it doesn’t help you answer a question a Series A investor will ask, it’s probably too early.